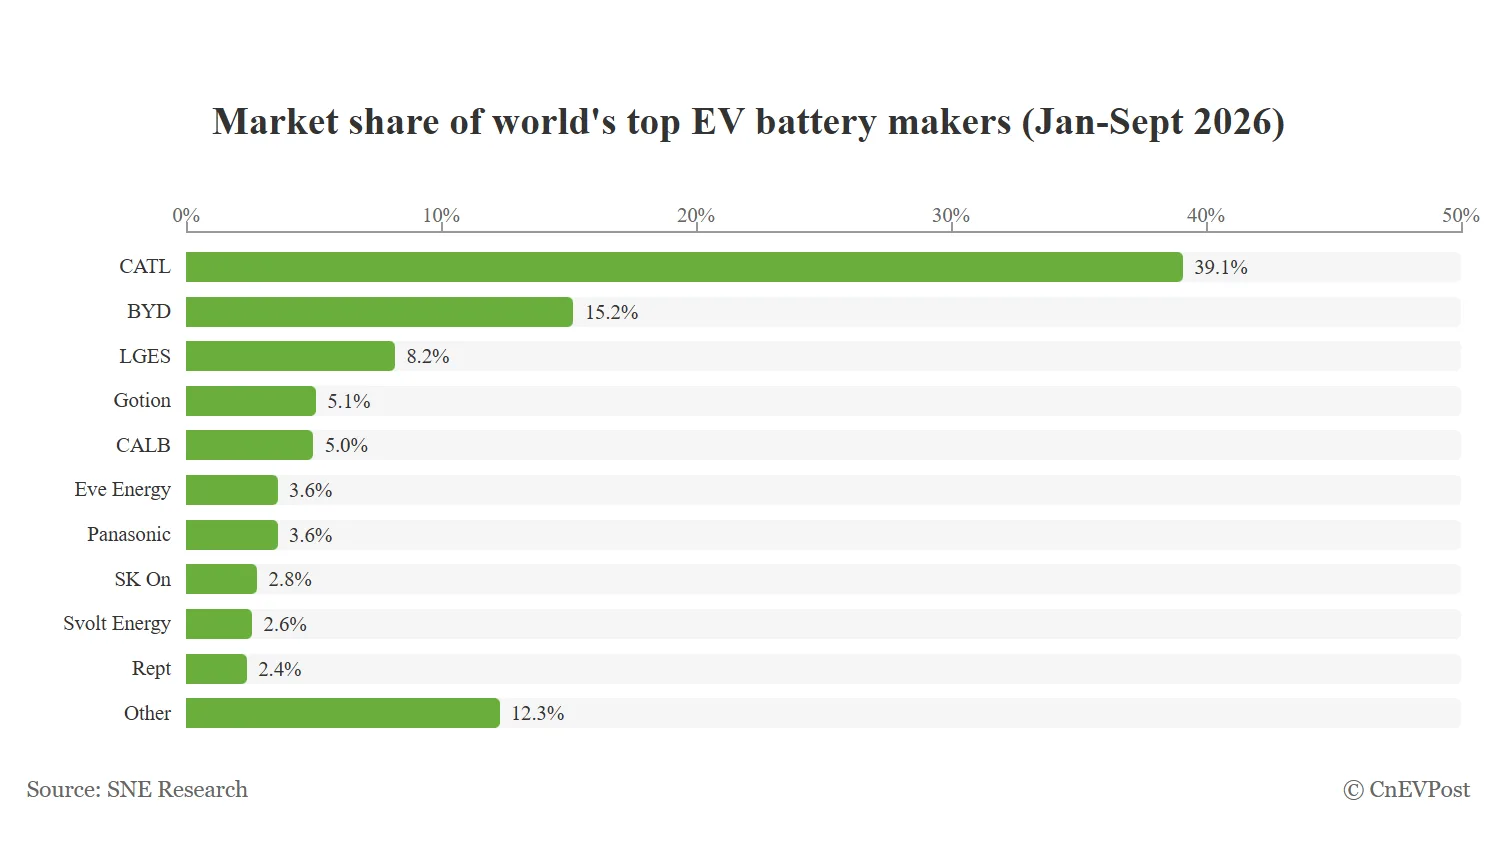
The global electric vehicle (EV) battery market in the first three quarters of 2026 is led by CATL, which holds a commanding share of nearly 40%. This marks the company as the foremost supplier in the expanding EV battery sector during this period.
Following CATL, BYD maintains a significant presence with around 15% of the market, while LG Energy Solution (LGES) comes third among the top suppliers worldwide. Together, these companies represent a dominant force in the supply chain for EV batteries, driven largely by increasing electric vehicle adoption globally.
Other notable battery manufacturers include Gotion, CALB, Eve Energy, Panasonic, SK On, and Svolt Energy, each contributing to the competitive landscape but trailing behind the market leaders. The collective market share of these firms reflects ongoing efforts to expand production capacity and improve battery technology to meet rising demand.
The data underscores the consolidation of manufacturing capacity predominantly in a handful of powerful players, with Chinese companies particularly prominent. This concentration may influence pricing, innovation rates, and supply stability as the industry grows.
As EV adoption continues to accelerate worldwide, battery makers are investing in new technologies such as solid-state batteries and increased energy density. Understanding these market shares provides insight into supply dynamics that affect automakers, consumers, and energy policy alike.